
Britain is not a very shouty place. Indeed, Andy Burnham is not a very shouty man. But the aspirations he laid out in his speech could change the mood music and, importantly for investors, create opportunities.
There may be a temptation to read every movement in the bond market as a judgement on government but that would be unwise. Government bond yields have been rising across several major economies, with oil prices, geopolitical tensions, inflation expectations and the outlook for interest rates all playing a part. The Bank of England itself has highlighted the effect of geopolitical tensions and higher energy prices on financial markets. Britain has its own fiscal challenges, certainly, but the gilt market is not operating in a British vacuum.
For long-term investors, therefore, perhaps the more interesting question is not what the bond market thought of Burnham’s speech, but what the economic direction he described might actually require.
There was plenty of ambition. More housing, investment in infrastructure, reform of social care, greater regional economic power and intervention to improve the capacity of the electricity grid all point towards a more active state. Burnham has previously promised a major council house building programme, while the Government has allocated almost £10 billion towards more than 70,000 affordable and social homes. At the same time, Chancellor John Healey continues to insist that the Government will operate within its fiscal rules.
The sum of the aspirational parts will bring investible opportunity. If the ambition is to build more without abandoning fiscal discipline, private capital potentially becomes an important part of the equation. Private equity, infrastructure capital and private credit already provide funding in areas ranging from housing and renewable energy to transport, technology and growing regional businesses. The investment opportunity is not simply in financing government projects, but in identifying the companies, assets and supply chains that could benefit if policy turns into sustained investment.
There is a demographic dimension too. Britain is ageing, which is normally presented principally as a fiscal burden. Yet demographic pressure also creates investment requirements. More appropriate housing, later-living developments, healthcare infrastructure and new models of social care all require physical assets, businesses and capital. Building more of what an older society needs can turn part of a structural challenge into an investible theme.
None of this removes risk and the October Budget will provide considerably more detail about how ambition is to be reconciled with the public finances. Business also wants greater clarity about future costs and taxation, while Burnham’s proposed expansion of public involvement in areas including energy infrastructure raises legitimate questions about where government ends and private capital begins.
Markets should expect some bumps but investors also need direction, and perhaps that is the more interesting change. After a long period in which Britain has often appeared to debate its constraints more enthusiastically than its possibilities, there is at least an emerging argument about what the country intends to build.
For investors, purpose does not guarantee returns. It does, however, help identify where future demand for capital might emerge. That is a better starting point than many might have feared.
1st October 2026
For much of the US / Iran conflict, investors have understandably watched two things like hawks: equity markets and the oil price. Both offer an immediate reading of how worried markets are and, with the Strait of Hormuz still operating to the tune of a geo-political hokey cokey, whether a geopolitical crisis is becoming a very real global economic one.
Yet with all that said, perhaps the more interesting consequences will take much longer to appear.
The surprise of the oil shock has not simply been that prices rose, but that they did not rise further. China provides part of the explanation. Having spent years accumulating enormous strategic reserves of crude, investing in renewable energy and electrified transport and building an industrial economy capable of substituting one source of energy or raw material for another, Beijing entered the crisis with options.
When Gulf supplies were interrupted, China could reduce imports and draw upon inventories. It could restrict refined product exports, reduce domestic consumption and shift transport demand. Its manufacturers even demonstrated an ability to substitute coal for oil derived inputs in some petrochemical processes.
This underlines how much economic resilience is underwritten by geopolitical power. For decades the United States has enjoyed perhaps the greatest example of that power through the dollar. Its position as the world’s principal reserve currency helps create extraordinary international demand for dollar assets and gives America financial flexibility that other countries simply do not possess.
The Iran war is unlikely to change that suddenly but understanding the use of the dollar in this context might be the wrong question. The issue is not whether countries abandon the dollar tomorrow, but whether repeated geopolitical shocks encourage them – gradually – to build alternatives to systems dominated by America.
China’s response to the oil crisis does not depend upon finding an alternative supplier at the last minute. It has spent years reducing the economic leverage that an interruption can exert over it. Storage, renewable energy, electric vehicles, railways and alternative industrial processes collectively provide strategic optionality. Other countries may increasingly think about financial infrastructure in much the same way.
That introduces another way of calculating the cost of war to the United States. There is the obvious military expenditure, but there are also second order costs. Higher oil prices can feed inflation, complicating the task of the Federal Reserve. Greater defence spending adds to already substantial fiscal demands. Disrupted trade reduces global growth and every demonstration of America’s willingness to use its military and financial power provides another incentive for rivals to reduce their exposure to both.
None of this means the dollar is about to lose its reserve status. The depth of US capital markets, liquidity of Treasury securities and absence of a credible alternative remain formidable advantages. It does, however, suggest a gradual movement towards a world in which countries value resilience as highly as efficiency.
That may be the investment lesson from this war. Investors have spent months asking where oil will trade next week and what another missile strike might do to equities tomorrow. Those questions matter, but the bigger changes may be taking place beneath them.
China has demonstrated that stockpiles, infrastructure and energy independence can alter the balance of a global commodity market. America has demonstrated again the reach of its military and financial power.
The question for the next decade is whether exercising that power ultimately strengthens the system on which it rests, or persuades more of the world to insure itself against it.
17th August 2026
There is something rather familiar about the way we are talking about artificial intelligence. The conversation is dominated by models, chips, valuations and astonishing demonstrations of what machines can now achieve. It reminds me a little of the early days of the internet when we obsessed over websites rather than fibre optic cables, or the railway age when we marvelled at locomotives without paying much attention to the steel beneath them.
Technology has a habit of distracting us from the infrastructure that makes it possible. Yet every discussion about AI eventually arrives at the same place, namely energy and somewhere, vast quantities of electricity were consumed to make it happen.
That has implications far beyond technology. For much of the last fifty years, developed economies have quietly assumed that electricity would simply be there. It was reliable, relatively inexpensive and largely invisible. Businesses worried about wages, interest rates and taxation. Even now. few board meetings devote much time to the availability of power itself.
But we are entering an era where economic growth increasingly depends upon digital infrastructure, and digital infrastructure depends upon energy. As AI becomes embedded into financial services, healthcare, manufacturing, logistics, defence and scientific research, electricity stops being an operational cost and becomes a strategic asset.
We have been here before not least in The Industrial Revolution which was as much about access to coal as it was steam engines per se. The twentieth century was not simply defined by the motor car but by oil. Entire alliances, conflicts and economies were and continue to be shaped by whoever controlled the fuel that powered progress.
It is entirely possible that the defining strategic resource of the twenty first century will not be data but the energy required to process it and this will change how we think about investment and public policy.
Countries that can generate abundant, dependable and increasingly clean electricity will enjoy an advantage that extends far beyond lower household bills. They will attract data centres, advanced manufacturing, pharmaceutical research, semiconductor fabrication and the thousands of businesses that increasingly depend upon computational power. Those that cannot may discover that capital is global and, unfortunately for them at least, remarkably mobile.
This is why debates around nuclear power, grid investment, battery storage, renewable generation and transmission networks are no longer separate conversations about environmental policy or infrastructure spending. They are discussions about economic competitiveness.
Artificial intelligence promises extraordinary gains in productivity, medical research, education and countless other fields. It may help us solve problems that have frustrated generations. But every technological leap creates second and third order consequences that deserve just as much attention as the breakthrough itself. One of those consequences is that energy becomes valuable in new ways.
Ironically, AI itself may become one of the tools that helps solve the challenge it creates. Smarter energy grids, more efficient generation, predictive maintenance, better storage management and optimised consumption all become more achievable through the very technology that is increasing demand. Throughout history, innovation has often found ways to ease the constraints created by earlier innovation and that should offer some cause for optimism rather than alarm.
AI is not simply another software cycle. It is the beginning of a profound reorganisation of the economy. The winners will not only be those writing better algorithms or building faster processors. They will also be those producing, transporting and managing the energy that underpins the entire system.
30th July 2026
Financial markets dislike very few things more than uncertainty. Indeed, they probably have a greater tolerance for the hip hop reference in this article heading than they have appetite for the ‘known and unknown unknowns’ of financial investment. They can usually accommodate the prospect of higher taxes, tighter regulation and even significant political change, provided the rules of the game are clear. What they struggle with is ambiguity. It is that question, rather than ideology alone, that increasingly surrounds Andy Burnham.
Burnham’s political career has never been built around financial markets. Unlike some of his contemporaries, he has not cultivated particularly close relationships with the City, private equity or institutional investors. His reputation has instead been forged through public service, regional government and his advocacy for greater devolution, particularly during his tenure as Mayor of Greater Manchester. That inevitably creates questions for investors. Not necessarily because markets assume he is hostile to business, but because they have relatively little evidence on which to judge how he would behave when confronted with difficult economic choices.
The challenge is that much of Burnham’s political identity has been constructed outside Westminster. His focus has been transport, housing, local investment and regional economic renewal rather than the mechanics of sovereign debt markets, pension fund confidence or international capital flows and for wealth managers and investors, that matters. Markets tend not to react to political personalities as much as they react to fiscal credibility and the experience of recent British governments has reinforced just how quickly gilt markets can impose discipline on any administration perceived to be taking excessive risks.
Burnham appears well aware of this reality. Recent speeches have deliberately emphasised adherence to existing fiscal rules, balanced public finances and the importance of maintaining market confidence. Indeed, his latest economic interventions suggest someone who recognises that governments today govern alongside financial markets rather than independently of them. This is an important signal because it suggests that while Burnham may favour a more interventionist state, greater regional investment and a different model of economic growth, he also understands that credibility cannot simply be declared. It has to be earned.
Of course, none of that removes uncertainty, many of the policies associated with Burnham remain deliberately broad. Greater devolution expanded infrastructure investment, more council house building and renewed industrial strategy are all relatively easy to support in principle. He has vision, which is very welcome among Labour MPs, but the more difficult questions concern funding, taxation and implementation remain. Will higher public investment be financed through borrowing, taxation or spending restraint elsewhere? Would capital gains taxation move closer to income tax? Could property taxation change? Would wealth taxes reappear as part of the political debate?
These questions remain at the time of writing open to conjecture rather than settled policy. Some economists sympathetic to Burnham have cautioned against relying on wealth taxes as a significant source of revenue, arguing they can prove economically inefficient while encouraging changes in investor behaviour.
This is an important distinction because financial markets are perfectly capable of adapting to higher taxation when it is predictable and accompanied by credible long term fiscal management. What unsettles markets is uncertainty over the direction of travel. For wealth managers, the objective should not be to predict political outcomes but to prepare portfolios capable of coping with multiple scenarios. Diversification across jurisdictions, careful use of tax allowances, maintaining liquidity where appropriate and regularly reviewing estate planning remain sensible disciplines regardless of who occupies Downing Street. Political cycles change far more frequently than long term investment objectives.
Perhaps the most conclusion for now is that Andy Burnham remains less an ideological risk than an informational one. Markets simply know less about him than they do about many previous prime ministers. That information gap naturally creates a degree of caution and over time that caution may fade if policy becomes clearer and fiscal discipline remains credible. Equally, if future announcements raise doubts over borrowing, taxation or government intervention, markets are unlikely to wait long before expressing their opinion.
For now, Burnham remains something of an unknown quantity. Not because investors expect the worst, but because they are still waiting to discover precisely which Andy Burnham would arrive in government. When will the real Andy Burnham stand up?
2nd July 2026
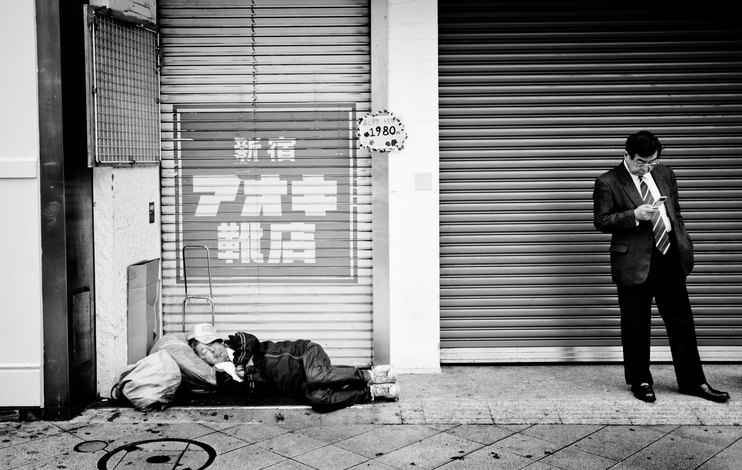
The modern investment market has become extraordinarily good at pricing visible risk. Interest rates move, markets respond. Conflict emerges, commodities spike. Inflation rises, valuations compress. Yet some of the most significant risks facing global investors today are not cyclical at all. They are structural, social and increasingly political. Rising inequality sits firmly in that category.
For many institutional investors, inequality has traditionally been viewed as a political issue, perhaps even a moral one, but not necessarily an investment issue. That position is becoming increasingly difficult to defend. A growing body of investor thinking now treats inequality as a systemic financial risk capable of undermining long term economic growth, political stability and ultimately portfolio performance itself.
This matters because the global economy increasingly resembles a two speed system. Asset owners have generally done well. Those without assets often have not. The post pandemic period accelerated that divide. Asset price inflation boosted the value of equities, property and alternative investments while wage growth struggled to keep pace with the real cost of living in many developed economies. The result is an increasingly fragile consumer base sitting underneath increasingly concentrated pools of wealth.
Consumer economies depend on broad participation. If younger generations are locked out of home ownership, if savings rates remain weak, if debt burdens rise while real incomes stagnate, the long term implications for consumption become unavoidable. Investors cannot rely indefinitely on financial engineering, AI productivity gains or market concentration to offset weakening demand fundamentals. At some point the underlying economy has to function for enough people to sustain growth.
That is why the current debate around artificial intelligence is so important. AI has the potential to deliver extraordinary productivity gains and create immense value. But investors are increasingly conscious that those gains may accrue disproportionately to those who already own capital, infrastructure and intellectual property. Even BlackRock chief executive Larry Fink has warned that AI risks widening wealth inequality further if ownership remains concentrated among a relatively small group of investors and technology firms.
This is where the issue becomes highly relevant for international investors, sovereign wealth funds, pension schemes and insurers. Large diversified investors cannot simply rotate away from systemic social risk. Unlike an individual company failure or even a sector downturn, inequality affects the operating environment of the entire market. It shapes taxation, labour stability, consumer demand, populism, geopolitical tension and regulatory intervention.
In many ways the parallels with climate risk are becoming clearer. Initially climate change was treated as a niche ESG concern. Over time investors realised it represented a macroeconomic and systems level challenge capable of reshaping entire industries and economies. Inequality is beginning to be viewed through a similar lens.
The implications for capital allocation are substantial. Firstly, investors are increasingly likely to demand better data around workforce resilience, pay structures, labour relations and human capital management. Traditional quarterly earnings analysis does not fully capture whether businesses are contributing to long term economic sustainability or extracting short term value at the expense of broader social stability.
Secondly, sectors dependent on discretionary consumer demand may face heightened scrutiny if middle income pressure intensifies further. Retail, housing, automotive finance and consumer credit markets all become more vulnerable when purchasing power weakens structurally rather than cyclically.
Thirdly, political intervention risk rises materially in unequal economies. Wealth taxes, regulatory intervention, rent controls, labour protections and restrictions on corporate behaviour become increasingly likely as governments attempt to respond to social pressure. Investors who ignore this dynamic risk mispricing entire markets.
There is also a geographical dimension emerging. Some economies are arguably better positioned than others to absorb technological disruption and demographic change. Markets with stronger social infrastructure, affordable housing supply, workforce mobility and long term industrial planning may ultimately offer more sustainable investment environments than those heavily dependent on asset inflation and financial concentration.
For international investors, this creates an uncomfortable but necessary question. Is modern capitalism drifting towards a model where financial markets continue to rise while the underlying social contract weakens beneath them?
None of this means investors should retreat from innovation, technology or global markets. Quite the opposite. But it does suggest that resilience will increasingly depend on understanding the interaction between economics, politics, demographics and social stability rather than treating them as separate disciplines.
The investment industry has spent years discussing sustainability in environmental terms. The next phase may be recognising that sustainable returns also require sustainable societies. If inequality continues to widen unchecked, investors may eventually discover that social instability behaves much like any other systemic risk. It starts gradually, compounds quietly and then reprices suddenly.
29th May 2026
During a business trip to Malta, it is clear that – whilst the shine may be coming off Dubai – this island is clearly benefiting
It was the moment the governments of the Gulf hoped would never arrive. When US president Donald Trump launched coordinated American and Israeli strikes on Iran, the Islamic republic responded by raining drones and missiles down on Dubai and the rest of the Gulf statelets. Over last weekend, the five-star Fairmont hotel was set ablaze, drones hit a series of sites across the city and the airport was closed, leaving tens of thousands stranded, and the estimated 240,000 British citizens living and working there unable to get out.
The states of the United Arab Emirates are all key allies of the US, so to the Iranian regime at least they must look like legitimate targets. But the attacks are a disaster for Brand Dubai. The city state has boomed over the last 25 years as a low-tax hub for the world’s wealthy and its most ambitious entrepreneurs. It had dozens of sleek new office buildings, luxury apartments, glitzy shopping centres and some of the most luxurious real estate in the world. Along with the rest of the Gulf, it has turned into an engine of prosperity. A GDP of $16bn in 2000 had by last year grown to $96bn. As Britain in particular imposed higher taxes, it became the preferred refuge for the rich.
Those expatriates were not looking to move to a war zone, of course. The conflict may be resolved quickly, and everything may get back to normal very rapidly. But if the conflict drags on for months, it will start to do very real damage. Dubai does not have the experience of defending itself from missiles and drone attacks in the way that Israel does. Its entrepreneurial population is very footloose. It is made up of people who have already decided they have no special attachment to the country they were born in, and you can’t expect them to have any greater attachment to the place where they have temporarily resettled. None of them will want to get caught up in a regional war. As soon as it is safe to do so, they will be off.
That means there is now a huge market for a low-tax mini-state to replace Dubai. The Caribbean is one obvious potential beneficiary – the Bahamas, the British Virgin Islands and the Cayman Islands are already significant offshore centres. Some of the smaller states of central America have already started to turn themselves into low-tax hubs. El Salvador, which has made bitcoin a legal currency, is one obvious example. There could be candidates coming forward in Europe. Malta already has lowish taxes and generous deals for expatriates. Albania and Montenegro are rapidly developing offshore industries. Italy has already captured much of the top-end of the market with its flat-tax deal. Even Gaza, with its peace plan overseen by Tony Blair and Jared Kushner, may emerge as a viable alternative, especially if it has committed military protection from Israel and the US. There is a long list of countries eager to capture some of the wealth Dubai was generating. None have Dubai’s infrastructure or critical mass yet. But they could build it quickly. The template is already there. It will just take political leadership to grab the opportunity.
The low-tax mini-state is one of the key innovations of the century so far. Digital communications have made it easier than ever to move from one place to another. There are few barriers to trade, so people can do business from anywhere. And relentless rising welfare bills and ageing populations mean the tax burden is constantly going up across most of the developed world, creating more incentives for people to get out. Dubai captured that market brilliantly. The war has created a huge gap in the market.
12th May 2026
It’s easy to feel overwhelmed by digital currency but to underestimate the potential of some of these initiatives would be a mistake. Among them are Stablecoins. These are often framed as a niche corner of crypto but for international investors, that misses the point. What is emerging is not simply a new asset, but a new layer of financial infrastructure, one that sits between traditional money and digital markets and is increasingly shaped by US strategic intent.
At their simplest, stablecoins are digital tokens designed to maintain a fixed value, typically pegged one-to-one with the US dollar. Leading examples such as USD Coin and Tether are backed by reserves that largely sit in cash and short-duration US Treasuries. That backing is critical because it defines what stablecoins really are: not speculative instruments like Bitcoin, but programmable, transferable cash equivalents.
For investors, that distinction changes how they should be viewed. Stablecoins are not, in most cases, a source of return. They are a tool for moving, holding and deploying capital with greater speed and flexibility than traditional banking rails allow.
The immediate benefit is liquidity. Stablecoins enable near-instant, 24/7 settlement across borders without reliance on correspondent banking networks. Capital can be repositioned quickly between markets, strategies and counterparties. For investors operating across jurisdictions, particularly in private credit, structured finance or emerging markets, that reduction in friction is meaningful. It shortens the distance between decision and execution.
There is also a more structural implication around yield and deposits. The reserves underpinning major stablecoins are typically invested in government debt, meaning the economic return sits with the issuer rather than the holder. That dynamic raises an obvious question: as digital cash becomes more embedded in financial markets, will investors continue to tolerate low or zero returns on traditional deposits? If stablecoin ecosystems begin to share yield, even partially, the competitive position of banks as deposit gatherers begins to shift. This is where stablecoins move from being a payments innovation to a funding and balance sheet story.
Perhaps the most underappreciated feature, however, is programmability. Because stablecoins operate on digital infrastructure, they can be embedded into automated processes, investment logic and tokenised assets. Capital can move not just quickly, but conditionally, based on pre-defined rules and over time, has the potential to reshape how portfolios are constructed and managed, reducing operational drag and increasing precision.
Overlaying all of this is the accelerating push by the United States to shape the market. This is not accidental. Stablecoins are, in effect, a digital extension of the dollar. As long as the dominant tokens remain dollar-denominated, they reinforce the currency’s global role, but in a more portable and accessible form. Investors and institutions can hold and transact in dollars without needing direct access to the US banking system.
This has two important consequences. First, it embeds ongoing demand for US assets, particularly short-term Treasuries, which form the backbone of stablecoin reserves. As the market grows, so too does structural demand for government debt. Second, it positions private issuers as distributors of digital dollars, allowing the US to extend its monetary influence without relying solely on a central bank digital currency model.
For international investors, the opportunity is clear. Stablecoins offer a more efficient way to move capital globally, access digital markets and engage with emerging forms of tokenised finance. They reduce friction and open new pathways for deployment.
Stablecoins are only as robust as the assets backing them and the frameworks governing them. Questions around reserve transparency, redemption rights and regulatory oversight remain central. They are a form of counterparty exposure, albeit one that sits outside traditional banking structures.
If stablecoins scale as expected, they have the potential to draw liquidity away from banks, alter funding dynamics and reshape elements of financial stability frameworks. For investors, the implications will not be confined to digital assets. They will be felt across credit markets, liquidity management and the cost of capital.
In that sense, stablecoins are not a side story. They are part of a wider transition in how money moves and how financial systems are organised. The US move to lead in this space reinforces a simple reality: as finance becomes more digital, the battle is not just for innovation, but for control of the underlying currency.
26th April 2026
Crypto has spent much of the past decade cultivating an aura of inevitability. From early adopters to institutional allocators, the narrative has steadily evolved from fringe experiment to “digital gold” and, in some quarters, a supposed hedge against everything from inflation to geopolitical instability. Yet the reality is more nuanced. Crypto is not a panacea and it is not an invincible asset class. Treating it as such risks repeating some very familiar financial mistakes.
Unlike traditional asset classes, which benefit from decades, if not centuries, of regulatory development, liquidity frameworks, and institutional oversight, crypto markets are still evolving in real time. Price formation is often driven less by underlying economic value and more by sentiment, flows, and momentum which underlines why , when confidence is strong, the upside can be dramatic. But this also creates fragility and when sentiment turns, there is often no real anchor to prevent sharp corrections.
You might conclude then that volatility is not just a feature of crypto; it is a defining characteristic. While proponents argue that this volatility reflects growth and opportunity, it also undermines the idea that it can serve as a reliable store of value. Assets that can lose significant portions of their value over short periods struggle to perform this role, particularly in times of broader market stress when diversification benefits are most needed.
The idea of crypto as a hedge against inflation has also proven inconsistent. In theory, limited supply, particularly in assets like Bitcoin, should provide protection against currency debasement. In practice, however, crypto has often traded in line with risk assets, particularly technology equities. During periods of rising interest rates and tightening liquidity, crypto markets have tended to fall alongside other speculative assets rather than act as a counterbalance which in turn prompts the question whether crypto is truly a new asset class or simply another expression of global liquidity cycles.
Around the world, policymakers are still grappling with how to treat crypto , be that as a currency, a commodity, a security, or something entirely new. This uncertainty creates ongoing risk for investors. Regulatory interventions can materially alter market dynamics overnight, from restrictions on exchanges to changes in taxation or outright bans. For an asset class that prides itself on decentralisation, its dependence on centralised infrastructure like exchanges introduces points of failure that regulators can and do influence – including its perception as being energy-intensive which attracts scrutiny from governments and investors alike.
There are also structural risks embedded within the ecosystem itself. The collapse of high-profile exchanges and projects in recent years has highlighted issues around governance, transparency, and counterparty risk. In many cases, investors have discovered that the protections they take for granted in traditional finance—segregation of assets, capital requirements, and clear legal recourse—are either absent or inconsistently applied in crypto markets. The result is a landscape where operational risk can be just as significant as market risk.
None of this is should imply that crypto lacks value or future potential. The underlying technologies of distributed ledgers, programmable assets, and decentralised finance are already influencing how financial systems evolve. But there is a difference between recognising potential and assuming inevitability.
History is littered with asset classes and innovations that were once considered unstoppable. The lesson is not that they failed entirely, but that their paths were far more volatile, contested, and uncertain than early narratives suggested. Crypto is likely to follow a similar trajectory. It may well become a meaningful part of the global financial system, but it will do so through cycles of correction, regulation, and reinvention, not through invincibility.
For investors, the implication is clear. Crypto should be approached with the same discipline applied to any other asset class and measured accordingly.
11th April 2026
In recent months, investors have been so fixated on the uncertain trajectories of AI valuations and “AI winners vs losers” narratives that we’re watching a classic misallocation of capital in real time. There’s an almost myopic tone in markets about generative models and software moats at a time when systemic risks like supply chains, logistics corridors and chokepoints in the physical economy are being materially repriced by geopolitical stress.
It’s striking, but not surprising: AI narratives live in a realm of abstraction whereas the real world still turns on the movement of physical goods through physical bottlenecks. That difference matters because the real economy still has bottlenecks that, if further disrupted, reverberate globally. None is more immutable today than the Strait of Hormuz, the narrow maritime corridor that accounts for nearly a fifth of global oil shipments and a disproportionate share of liquefied natural gas and bulk cargo flows. Its importance is not theoretical but structural. Any credible threat to its functioning instantly reprices energy markets, shipping rates, insurance premiums, and inflation expectations across interconnected supply networks.
Today’s escalation in U.S.–Iran tensions is a structural test. Market data shows oil benchmarks spiking, futures markets wrestling with a geopolitical risk premium, and investors stepping back from risk assets at the same time as AI “sell-offs” appear in tech indices. Perhaps this is all symptomatic of where the real fragilities in global capitalism lie. Software hype cycles can reverse without altering geopolitical energy flows but real disruption in Hormuz or the wider Middle East could be far more consequential to corporate earnings and consumer price levels than the latest OpenAI pricing model forecast ever will be.
AI will transform sectors over the long run, but that revolution is layered on top of supply chains that remain brittle and vulnerable to geopolitical strain. From Suez to Russia-Ukraine to COVID supply dislocations, markets have repeatedly underestimated the non-linear impacts of supply-chain shocks on inflation, trade, and growth. Today, the added dimension of a potential U.S.–Iran confrontation brings those vulnerabilities into sharp relief again. The very fact that oil, gold, and safe-haven assets are rallying alongside selling in tech suggests markets are repricing macro disruption risk rather than purely “AI risk.”
From an investment perspective, this is a timely reminder that real economy exposures matter: port operations, freight logistics, container capacity, shipping index derivatives, energy infrastructure, and supply-chain software platforms enabling resilience have real earnings and real pricing power when uncertainty spikes. Artefacts of AI valuations may outperform on narrative alone in the short term, but when real places like Hormuz are threatened, flows stop, insurers widen spreads, and the cost of capital rises.
The prudence of capital allocation should account for the interaction between digital evolution and physical scarcity. Supply chains are undergoing digitisation, but they remain governed by geography, geopolitics, and sovereign behaviour. In that sense, logistics and supply infrastructure are not just investments, they’re hedges against the very risks that current headline narrative cycles fail to price adequately.
25th February 2026